The inventory turnover ratio measures how many times a company sells and replaces its inventory in a period, usually a year. Calculate it by dividing cost of goods sold by average inventory (beginning inventory plus ending inventory, divided by two). A ratio of 4.8 means the stock turned over about every 76 days.
That’s the part every page on this topic gets right, and it’s the part that changes nothing on its own. In our experience the ratio is an output. It’s a scorecard for purchase decisions made months ago against a forecast, and the warehouse only reports the verdict. So this guide resolves the formula quickly, gives you benchmarks with the caveats they need, and spends its second half on the input that moves the number: forecast error.
What is the inventory turnover ratio?
Inventory turnover (also called stock turnover) is the number of times your average inventory is sold through and replaced over a period. Turn it four times a year and, on average, a dollar of stock sits for about three months before it becomes a dollar of cost of goods sold. Turn it twelve times and that same dollar sits for a month.
A high ratio usually means demand is strong and stock is moving. It also means less cash tied up, lower carrying cost, and less exposure to obsolescence and markdowns. A low ratio usually means the opposite: stock is sitting, capital is idle, and something in the buying process is out of step with what customers actually take.
The nuance most guides skip is that “high” has a failure mode too. A ratio that climbs because you’re chronically under-stocked looks great on the finance dashboard while the sales team watches customers walk. Turnover measures speed. It says nothing about whether you had the item when the order came in, which is why the teams that manage it well read it as a pair: turns and fill rate together, or neither one means much.
The inventory turnover ratio formula, worked through on real numbers
The inventory turnover formula:
Inventory turnover ratio = Cost of goods sold ÷ Average inventory
Where:
Average inventory = (Beginning inventory + Ending inventory) ÷ 2
One example, which we’ll carry through the rest of this piece. A regional distributor of consumer hardware closes the year with these figures:
| Input | Value |
| Cost of goods sold (12 months) | $24,000,000 |
| Inventory at start of year | $5,200,000 |
| Inventory at end of year | $4,800,000 |
| Average inventory | ($5,200,000 + $4,800,000) ÷ 2 = $5,000,000 |
| Inventory turnover ratio | $24,000,000 ÷ $5,000,000 = 4.8 |
The distributor turned its inventory 4.8 times in the year. Both inputs come straight off the financial statements, which is why turnover is one of the few operational metrics a CFO and a supply chain director calculate the same way. Two refinements if you can: average monthly balances rather than two endpoints, since a seasonal business looks leaner or fatter depending on which two months you pick, and compute it by segment, because a blended 4.8 can hide a 12 on consumables and a 1.5 on the long tail.
Now the mistake. Plenty of teams calculate turnover with revenue in the numerator instead of cost of goods sold, since revenue is the number everyone knows. If our distributor’s revenue was $36,000,000 on that $24,000,000 of COGS, the revenue version gives $36,000,000 ÷ $5,000,000 = 7.2. Same warehouse, same stock, and the ratio just improved by 50%. Revenue includes margin and inventory is valued at cost, so dividing one by the other inflates the result by exactly your gross margin. Benchmarks are published on the COGS basis, so a revenue-based ratio makes you look better than every peer for reasons that have nothing to do with inventory. If someone quotes you a turnover figure that seems high, ask which numerator they used.
Days of inventory on hand: the same number, read as time
Days of inventory on hand (DIO, also called days sales of inventory or DSI) converts the turnover ratio into a number of days:
Days of inventory on hand = 365 ÷ Inventory turnover ratio
Or, if you’d rather skip the ratio:
Days of inventory on hand = (Average inventory ÷ Cost of goods sold) × 365
For the distributor: 365 ÷ 4.8 = 76 days. Check it the other way: ($5,000,000 ÷ $24,000,000) × 365 = 76 days. A dollar of stock sits, on average, for about two and a half months before it’s sold.
Turns and days describe the same fact, and both exist because different people need to act on it. Finance reports in days because days plug straight into the cash conversion cycle: days of inventory plus days sales outstanding minus days payables outstanding tells the treasurer how long the company’s cash is out of reach. Operations reports in turns because turns describe the rhythm of replenishment: how many times a year the buyer has to be right. When a controller says inventory is at 76 days and a planner says it’s turning 4.8 times, they’re agreeing.
Days sales of inventory is the same calculation under a different name, as is “days inventory outstanding.” The one variation to watch is whether someone used 365 days or working days, which changes the result by about a third and makes cross-company comparison meaningless unless you know which convention applied.
The days view has one practical advantage: it’s easier to feel. Turnover falling from 4.8 to 4.0 sounds abstract. The same stock sitting for 91 days instead of 76, two extra weeks of cash parked on a shelf, tends to get a purchase order review scheduled.
What is a good inventory turnover ratio? Benchmarks by industry
A cross-industry benchmark is close to useless, and we’d rather say that plainly than publish one. A grocer turning stock 12 times a year is healthy. A furniture retailer at 12 would be running on empty. Perishability, ticket size, assortment depth and lead times set the range for each sector before management quality has any say. The table below gives typical bands by retail sector, anchored to the latest 10-K filings of named public companies, so at least the definition is consistent (cost of goods sold over average inventory, annual).
| Sector | Typical turns per year | Days of inventory on hand |
| Grocery and supermarket | 12 to 16 | 23 to 30 |
| Convenience stores | 12 to 20 | 18 to 30 |
| Pharmacy | 11 to 15 | 24 to 33 |
| Fast fashion | 12 to 15 | 24 to 30 |
| Electronics and consumer tech | 4.5 to 8 | 46 to 81 |
| Pet supplies | 5 to 10 | 37 to 73 |
| Sporting goods | 3 to 6 | 61 to 122 |
| General apparel | 2 to 6 | 61 to 183 |
| Home goods and housewares | 2.5 to 5 | 73 to 146 |
| Furniture | 2 to 4 | 91 to 183 |
| Aftermarket auto parts | 1.3 to 1.6 | 228 to 281 |
Source: sector bands and 10-K anchors compiled by AisleStock’s inventory turnover benchmarks, verified June 2026. Ranges are directional. Named anchors from those filings span Kroger at 16.3 turns and Costco at 13.0 down to Home Depot at 4.5 and AutoZone at 1.4.
Two readings matter more than any single row. First, the spread inside a sector is wide: general apparel runs from 2 to 6 turns depending on format, so “apparel averages 4” tells a fast-fashion chain and a tailored menswear brand equally little. Second, manufacturers and B2B distributors typically sit below the retail categories they supply, because their inventory includes raw material and work in progress and their supplier lead times are longer. One industrial distributor in our 2026 accuracy report carries 7,500 stocked SKUs against 12-month supplier lead times; a turnover ratio that would alarm a grocer is structural for a business like that, and the deployment-by-deployment results show how different the portfolios behind these numbers are.
Which leaves the benchmark that actually holds: your own trend. Same business, same categories, same definition, quarter over quarter, is the only comparison that controls for everything the industry table can’t. If your turns are rising while fill rate holds, you’re doing this well, whatever the sector band says. If they’re flat for six quarters while the team keeps launching inventory projects, the next section is about you.
Why your turnover ratio is stuck, and why it is not a warehouse problem
When turnover stalls, the response is usually a list. Renegotiate supplier terms for smaller, more frequent deliveries. Run a markdown program on the slow movers. Tighten cycle counts. Rationalize the SKU catalog. Reorganize the warehouse so the fast movers are nearer the dock. All of these are sensible, and every one of them moves the ratio at the margin, because every one of them acts on stock that is already in the building.
Inventory sits because it was bought. That sounds obvious until you follow the timeline. The purchase order for the stock now clogging bay 14 was cut against a demand forecast three, six, sometimes twelve months ago, depending on your lead times. The forecast said the item would sell at a certain rate. It didn’t. The buying decision was correct given the number it was handed, and the number was wrong. By the time the warehouse team sees the excess, the only tools left are the expensive ones: discount it, move it, or write it off.
The same timeline runs in reverse for the items you keep running out of. A forecast that under-called demand on a rising SKU produced a purchase quantity that was too small, and no amount of warehouse efficiency puts units on a shelf that were never ordered. In practice most companies have both problems at once, in the same week, which is why turnover and service level can both look mediocre while every inventory project reports success.
Here is the test we suggest before the next warehouse initiative. Take your twenty highest-value excess SKUs and pull the forecast that was live when each one was last ordered. Then do the same for your twenty worst stockouts. If the forecast was materially wrong in most of the forty cases (and in our experience it will be), the constraint on your turnover ratio sits one system upstream of the warehouse. The companies in our accuracy report started from exactly this position. Each one had its new forecast benchmarked against the forecast they already ran, on the same SKUs and the same periods, and the gap between the two forecasts was the gap the inventory had been absorbing.
Forecast error is the lever
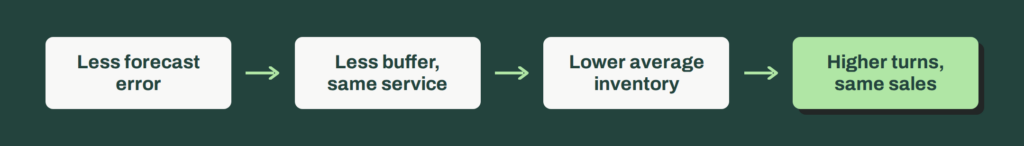
The mechanism runs in four steps, and each one is arithmetic rather than opinion.
Lower forecast error means less buffer for the same service level. Safety stock is sized against demand uncertainty, and once you have a forecast, the uncertainty that matters is the forecast’s error, measured as the standard deviation of forecast minus actual. Halve the error and the statistical buffer needed to hit a 95% service level halves with it, because the buffer is proportional to that standard deviation.
Less buffer means lower average inventory. Average inventory is roughly cycle stock (half an order quantity, on average) plus safety stock. Cycle stock is set by how you order. Safety stock is set by how well you forecast. Cut safety stock and the average falls by the same dollar amount, with no change in sales and no change in the order cadence.
Lower average inventory means higher turns at identical sales. Cost of goods sold, the numerator, didn’t move. The denominator did. Same demand, same revenue, same service level, higher turnover ratio.
Back to the distributor. Suppose its $5,000,000 of average inventory is $3,000,000 of cycle stock and $2,000,000 of safety stock. A forecasting program cuts the standard deviation of forecast error by 30%, which is the kind of reduction our accuracy report documents across a range of portfolios. Safety stock falls by 30%, to $1,400,000. Average inventory drops to $4,400,000. Turnover rises from 4.8 to 5.5 turns, and days of inventory fall from 76 to 67, nine days of cash back, at the same COGS and the same fill rate. Compare that with a well-executed order quantity project that trims cycle stock by 5%: average inventory to $4,850,000, turnover to 4.95. Both are worth doing. Only one of them changes the shape of the business.
The report’s findings are about forecast error, and we keep them separate from inventory outcomes on purpose, since reorder policy and planner behavior decide how much of a better forecast reaches the shelf. With that boundary stated, the downstream results were large: better forecasts cut overstock by up to 50% in one deployment, and what a better forecast is worth downstream walks through the inventory, working capital and planner-hour outcomes one at a time. To run the mechanism on your own numbers, start by learning to measure forecast error with MAPE and WMAPE at the level you buy at. The standard deviation of that error is the number that drives everything above.
How to improve inventory turnover over the next two quarters
Sequence matters more than effort here. Teams that start with the slow movers feel productive for a quarter and then watch the excess rebuild, because the process that created it is still running. This order works.
- Measure forecast error at SKU level before touching anything else. Pull two years of forecast and actual by SKU-location, compute WMAPE and bias, and compute the standard deviation of error per item. This takes a week and it’s the diagnostic for everything that follows. If you can’t produce the historical forecast, that finding alone says something about how the buying decisions were made.
- Segment by volume and variability. An ABC-XYZ grid, value crossed with predictability, tells you where precision pays. High-value, volatile items justify daily attention and the best forecast you can produce. Low-value, stable items justify automation and a buffer nobody reviews. Undifferentiated policies overprotect one half of the portfolio and underprotect the other, and both halves drag on turns.
- Reset safety stock against measured error, not against a flat rule. Most buffers we see were set as “two weeks of demand” or “20% over forecast” years ago and never recalculated. Replace the rule with a statistical buffer per segment using the error from step one; the six methods and the service-level table are in our guide to how to reset your safety stock formula.
- Then, and only then, deal with the slow movers already sitting there. Rank excess by value per SKU, redeploy what can sell elsewhere, promote what can’t, and liquidate the rest. This is the step most programs start with, and it’s the right fourth step. Once the forecast underneath has improved, what you clear stays cleared.
Everything on that list is one of the seven levers of inventory optimization, and forecast accuracy goes first because the other six all take the forecast as an input. Two quarters is a realistic horizon for the first three steps to show up in the ratio, because the stock bought against the old forecast has to sell through before the stock bought against the new one takes its place. Turnover is a lagging indicator by construction. Forecast error, measured monthly, is the leading one, and it’s the number to watch while you wait.
This is the work DemandForecast.ai does on the front end of that sequence: producing SKU-level forecasts with measurably lower error than the incumbent, in your own metric, so that steps two through four have a better number to work from. The turnover improvement follows from the arithmetic above; the forecast is the part that has to be earned.
Inventory turnover calculator
Enter your cost of goods sold, beginning inventory and ending inventory, and pick your sector. The calculator returns your inventory turnover ratio, your days of inventory on hand, and where you sit inside the sector band from the table above. It runs in your browser and nothing is stored. If you want to see the forecast error lever in action, enter your safety stock as a share of average inventory and reduce it by the error improvement you’re targeting; the second result shows the turns and days you’d reach at the same sales.
Inventory turnover calculator
Turns, days of inventory on hand, your sector band, and what a lower forecast error would do to all three.
Your results
Inventory turnover ratio
4.8turns per year
Days of inventory on hand
76days
Average inventory
$5,000,000
One extra turn would release
$862,000
Electronics and consumer tech typically turns 4.5 to 8 times a year (46 to 81 days). You are within the band
After a 30% cut in forecast error
Turnover ratio
5.5
Days on hand
67
Inventory released
$600,000
Same cost of goods sold, same sales, same service level. Only the buffer changed.
Runs in your browser. Nothing you enter is stored or sent anywhere. Sector bands are typical ranges anchored to the latest 10-K filings of named public companies, compiled by AisleStock (June 2026), and are directional. The benchmark that holds is your own trend.
Calculator spec for the build: inputs are COGS (currency), beginning inventory, ending inventory, sector dropdown (the eleven rows in the benchmark table plus “Manufacturing / B2B distribution, no band”), and an optional “safety stock share of average inventory” slider with a “forecast error reduction %” field. Outputs are turnover ratio (one decimal), days of inventory on hand (whole days), position within the sector band (below, within, above, with the band shown), and, when the optional inputs are filled, the projected turnover and days after the safety stock reduction. Pre-fill with the article’s example ($24,000,000 / $5,200,000 / $4,800,000, Electronics and consumer tech) so the first result reads 4.8 turns and 76 days. Show the COGS-not-revenue reminder as helper text under the first field. CSV download of inputs and outputs.